Taxing tips: what applies in hospitality
When is a tip tax-free and when not? §3 No. 51 EStG, card payments, service charges and documentation, what restaurateurs need to know about taxing tips.
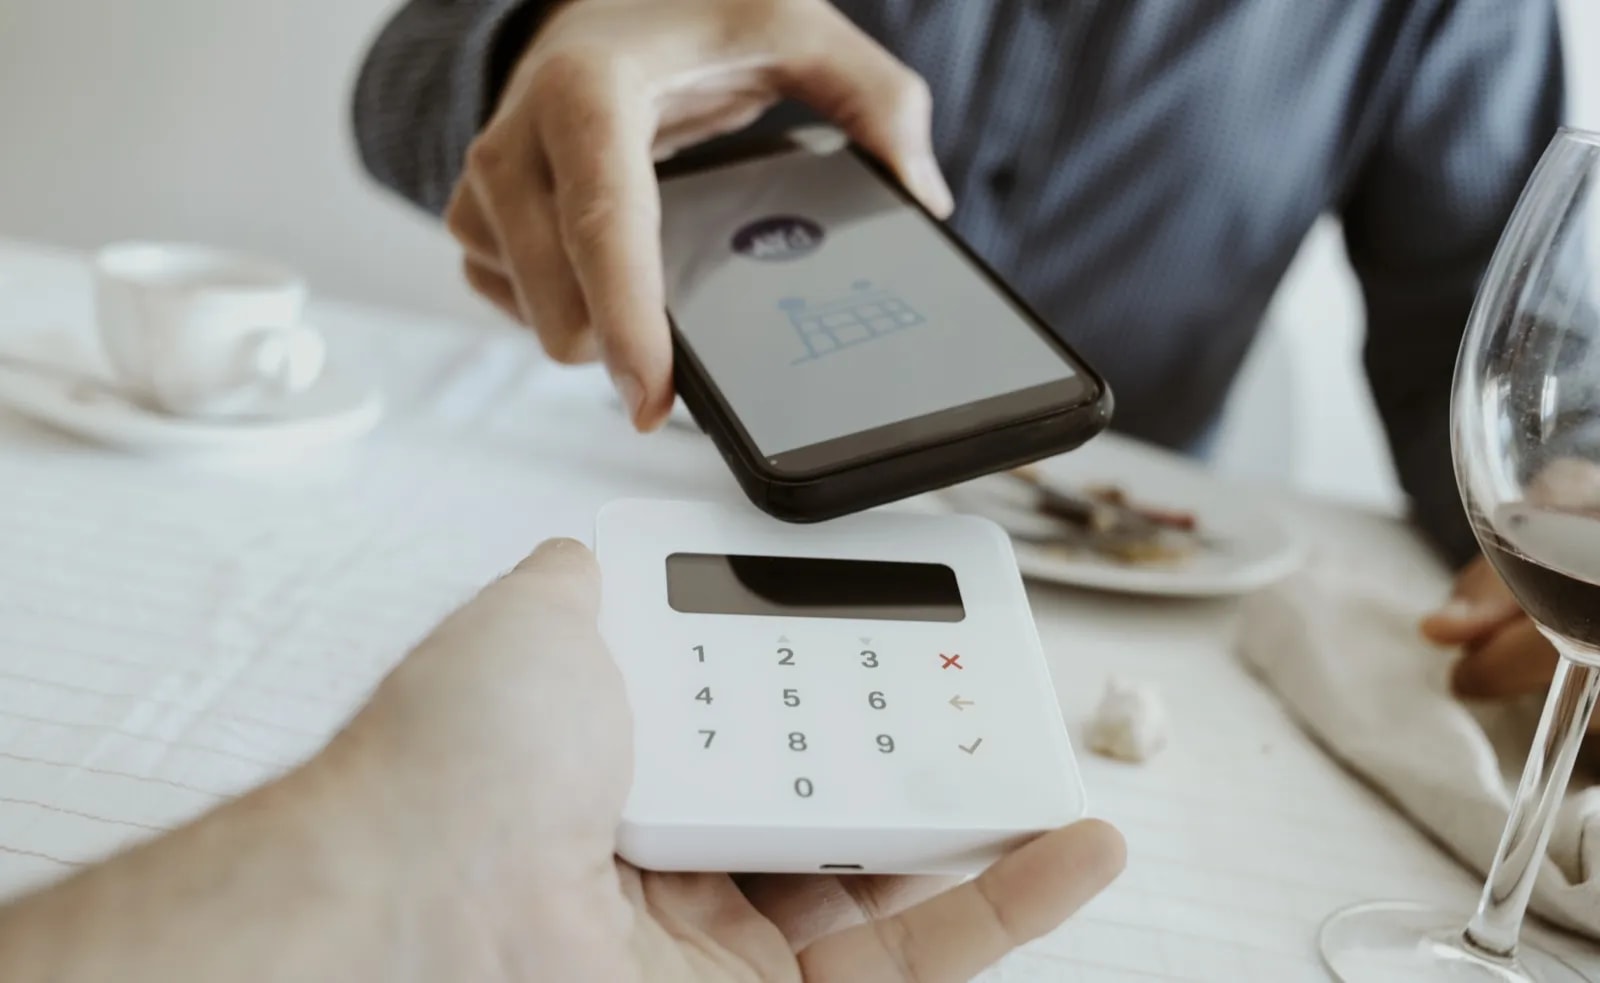
Tips are part of everyday life in the restaurant business — yet when it comes to taxes, they still cause uncertainty. Is the money tax-free? Does that also apply to card payments? And what happens when the boss is handed something personally?
This guide gives you a compact summary of how tips are taxed in the German restaurant business: the rules, what's customary and what to watch out for in practice.
Are tips tax-free?
In most cases, yes. The legal basis is §3 Nr. 51 of the Einkommensteuergesetz (EStG, the German Income Tax Act): tips that an employee receives from guests are tax-free without any limit — and exempt from social security contributions as well. There has been no cap since 2002.
That means the employee neither has to declare the tips in their tax return nor pay any contributions on them. The condition, however, is that it is a genuine tip within the meaning of the law.
The four conditions for tax exemption
For a tip to remain tax-free, four conditions must be met at the same time:
- Voluntary: the guest pays of their own accord; nobody obliges them to.
- In addition to the invoice amount owed.
- Personally to the employee — as recognition for their service.
- No legal entitlement: it is neither contractually agreed nor fixed in amount.
If any one of these conditions is missing, the payment is no longer a tax-free tip but taxable wages.
Tips for the boss: this is where it becomes taxable
Important: the tax exemption only applies to employees. If the owner or self-employed restaurateur receives the tip themselves, it is not tax-free. For tax purposes it counts as business income and is subject to income tax.
So if you stand behind the bar alone or collect tips as a self-employed person, you have to record and pay tax on this income.
A service charge is not a tip
If the bill shows a fixed item such as a "service fee" or a percentage-based service charge, that is not a voluntary tip. Such amounts are fixed from the outset, are part of the remuneration and are therefore subject to tax and social security contributions.
The same applies if the employer withholds tips and pays them out as part of wages. As soon as the money flows through the employer as a wage component, the tax exemption is gone.
Tips on card payments
More and more guests pay cashless — and add the tip right at the terminal. Even then it remains tax-free for the employee, provided 100% of the amount is passed on to them.
Since the money first lands in the business's account, clean bookkeeping is crucial here: the tip must be recorded separately from revenue and paid out to the employee in full. Unlike with cash, a payment through the till is traceable at any time — that helps you with the tax office, but it also demands correct separation.
Practical tip: Always record digital tips under a dedicated line item, never within regular revenue. That keeps it traceable that the amount was passed through and not retained as business income.
Documentation: the sore spot
Tax-free doesn't mean "doesn't have to be recorded". Precisely because large, lump-sum payouts attract the tax office's attention, the rule is: better to document daily and precisely than to make rough weekly estimates. Clean records per day and per employee protect you if an audit ever comes.
The amount matters too: exceptionally high tips — five-figure sums, for instance — are no longer recognized as tax-free tips by the fiscal courts, because they go beyond the usual scale. For everyday restaurant life this isn't an issue, but it's good to know.
Tips for daily practice
- Separate tips from revenue — cash and digital alike, from day one.
- Pass on 100% of card-payment tips, otherwise they become taxable business income.
- Set transparent distribution rules: even if the boss collects the money in trust and splits it among the team, it stays tax-free — as long as it doesn't come from the employer.
- Record owner tips: if you receive tips yourself, you must declare them as income and pay tax on them.
- When in doubt, ask your tax advisor — in individual cases, the line between a tip and wages is a fine one.
Conclusion
Tips given to employees in the restaurant business are fundamentally exempt from tax and social security contributions — as long as they are voluntary, paid on top and flow directly to the employee without any legal entitlement. They become taxable for the owner personally, for fixed service charges and whenever the employer pays them out as wages. With card payments, clean separation is what counts.
A POS system that records tips separately from revenue takes the documentation off your hands. Servire reports tips — cash and card — separately and keeps them traceable for reporting and the tax office. Learn more on the feature overview. To see how the tax office audits your till overall, read the guide on the Kassennachschau.